
Goal-Based Portfolio Construction for Retirement Income Planning
Match spending needs to time horizons: near-term expenses in stable assets, long-term growth compounding untouched. See exactly how many years of spending are covered.

Trusted by advisory firms across North America

Why 60/40 Fails Retirement Portfolios
Traditional allocation ignores the question that matters: "When will I need this money?"
Market drops in early retirement devastate portfolios. A retiree needing $80K next year with that money in equities faces a forced sale during a downturn. Traditional allocation doesn't protect against this.
Mapping spending needs to time horizons, matching assets to liquidity requirements, rebalancing across buckets. That's hours per client in spreadsheets. That doesn't scale to 100 retirees.
"Should I sell?" When near-term expenses are already in stable assets, the answer is simple: "The next 3 years are covered. Stay invested."
How Goal-Based Portfolio Construction Works
Match spending to time horizons and build retirement portfolios around real needs
Define Spending by Time Horizon
Enter annual spending needs or import a cash flow schedule from planning software. Organize into short-term (0-3 years), medium-term (3-10 years), and long-term (10+ years) buckets.
Match Assets to Liquidity Needs
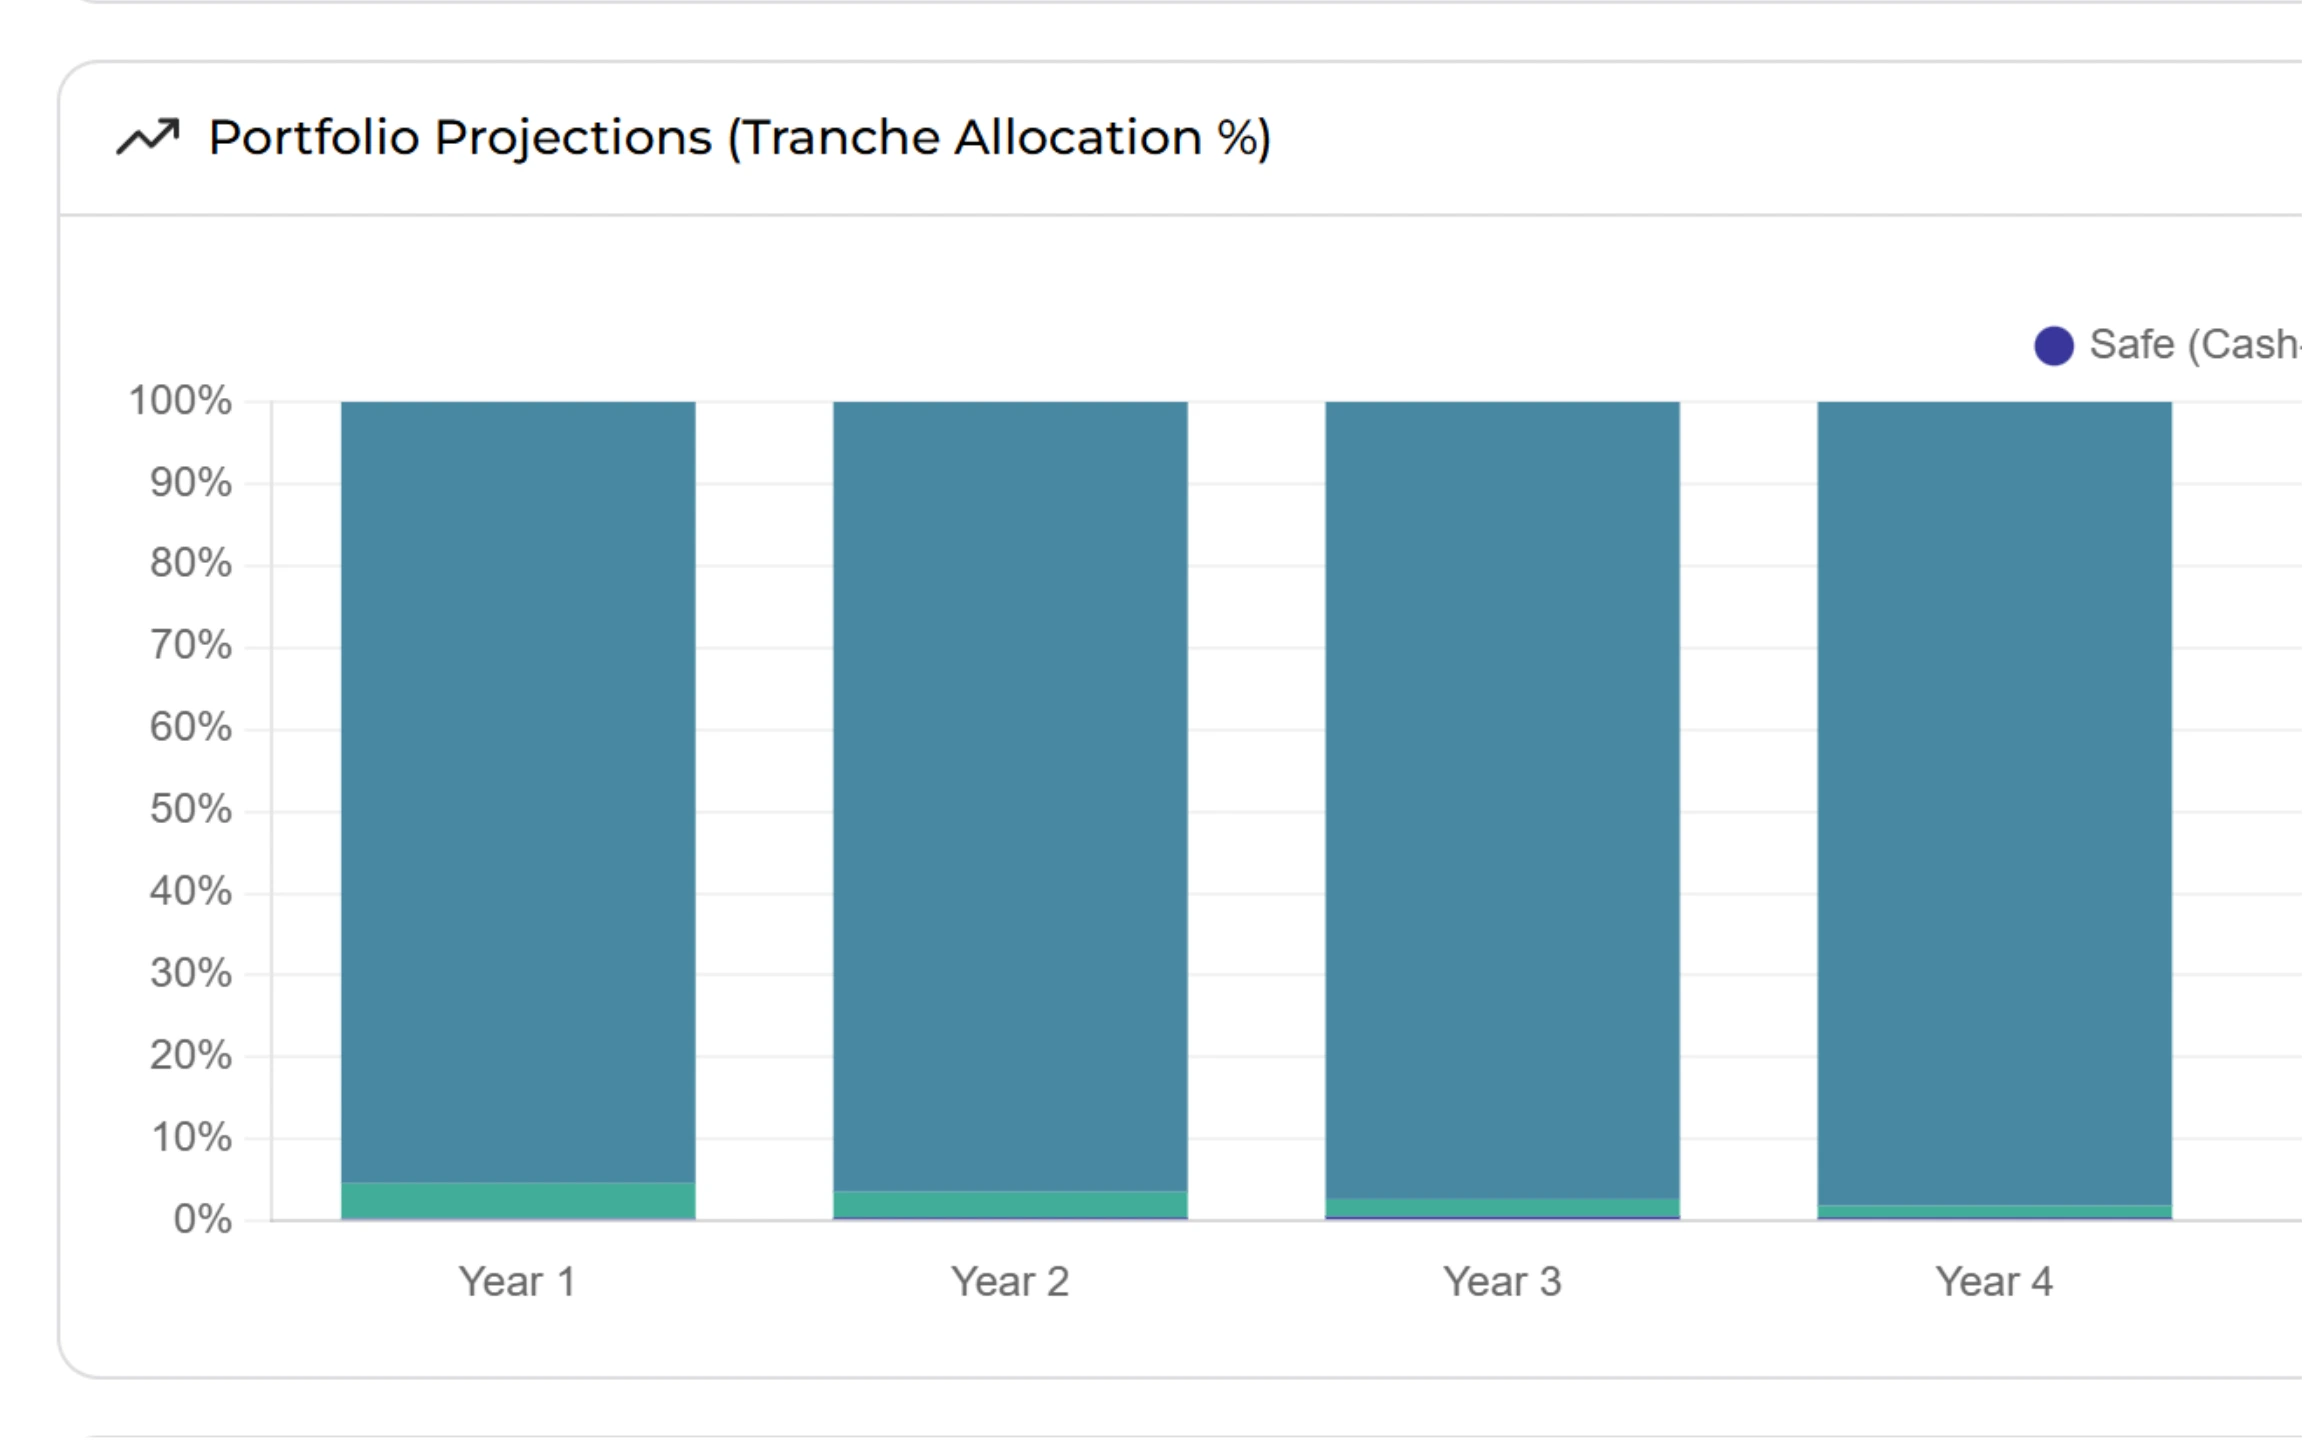
Get a recommended allocation for each bucket based on time horizon and risk tolerance. Then edit it. Each dollar sits in the right place for when it's needed.
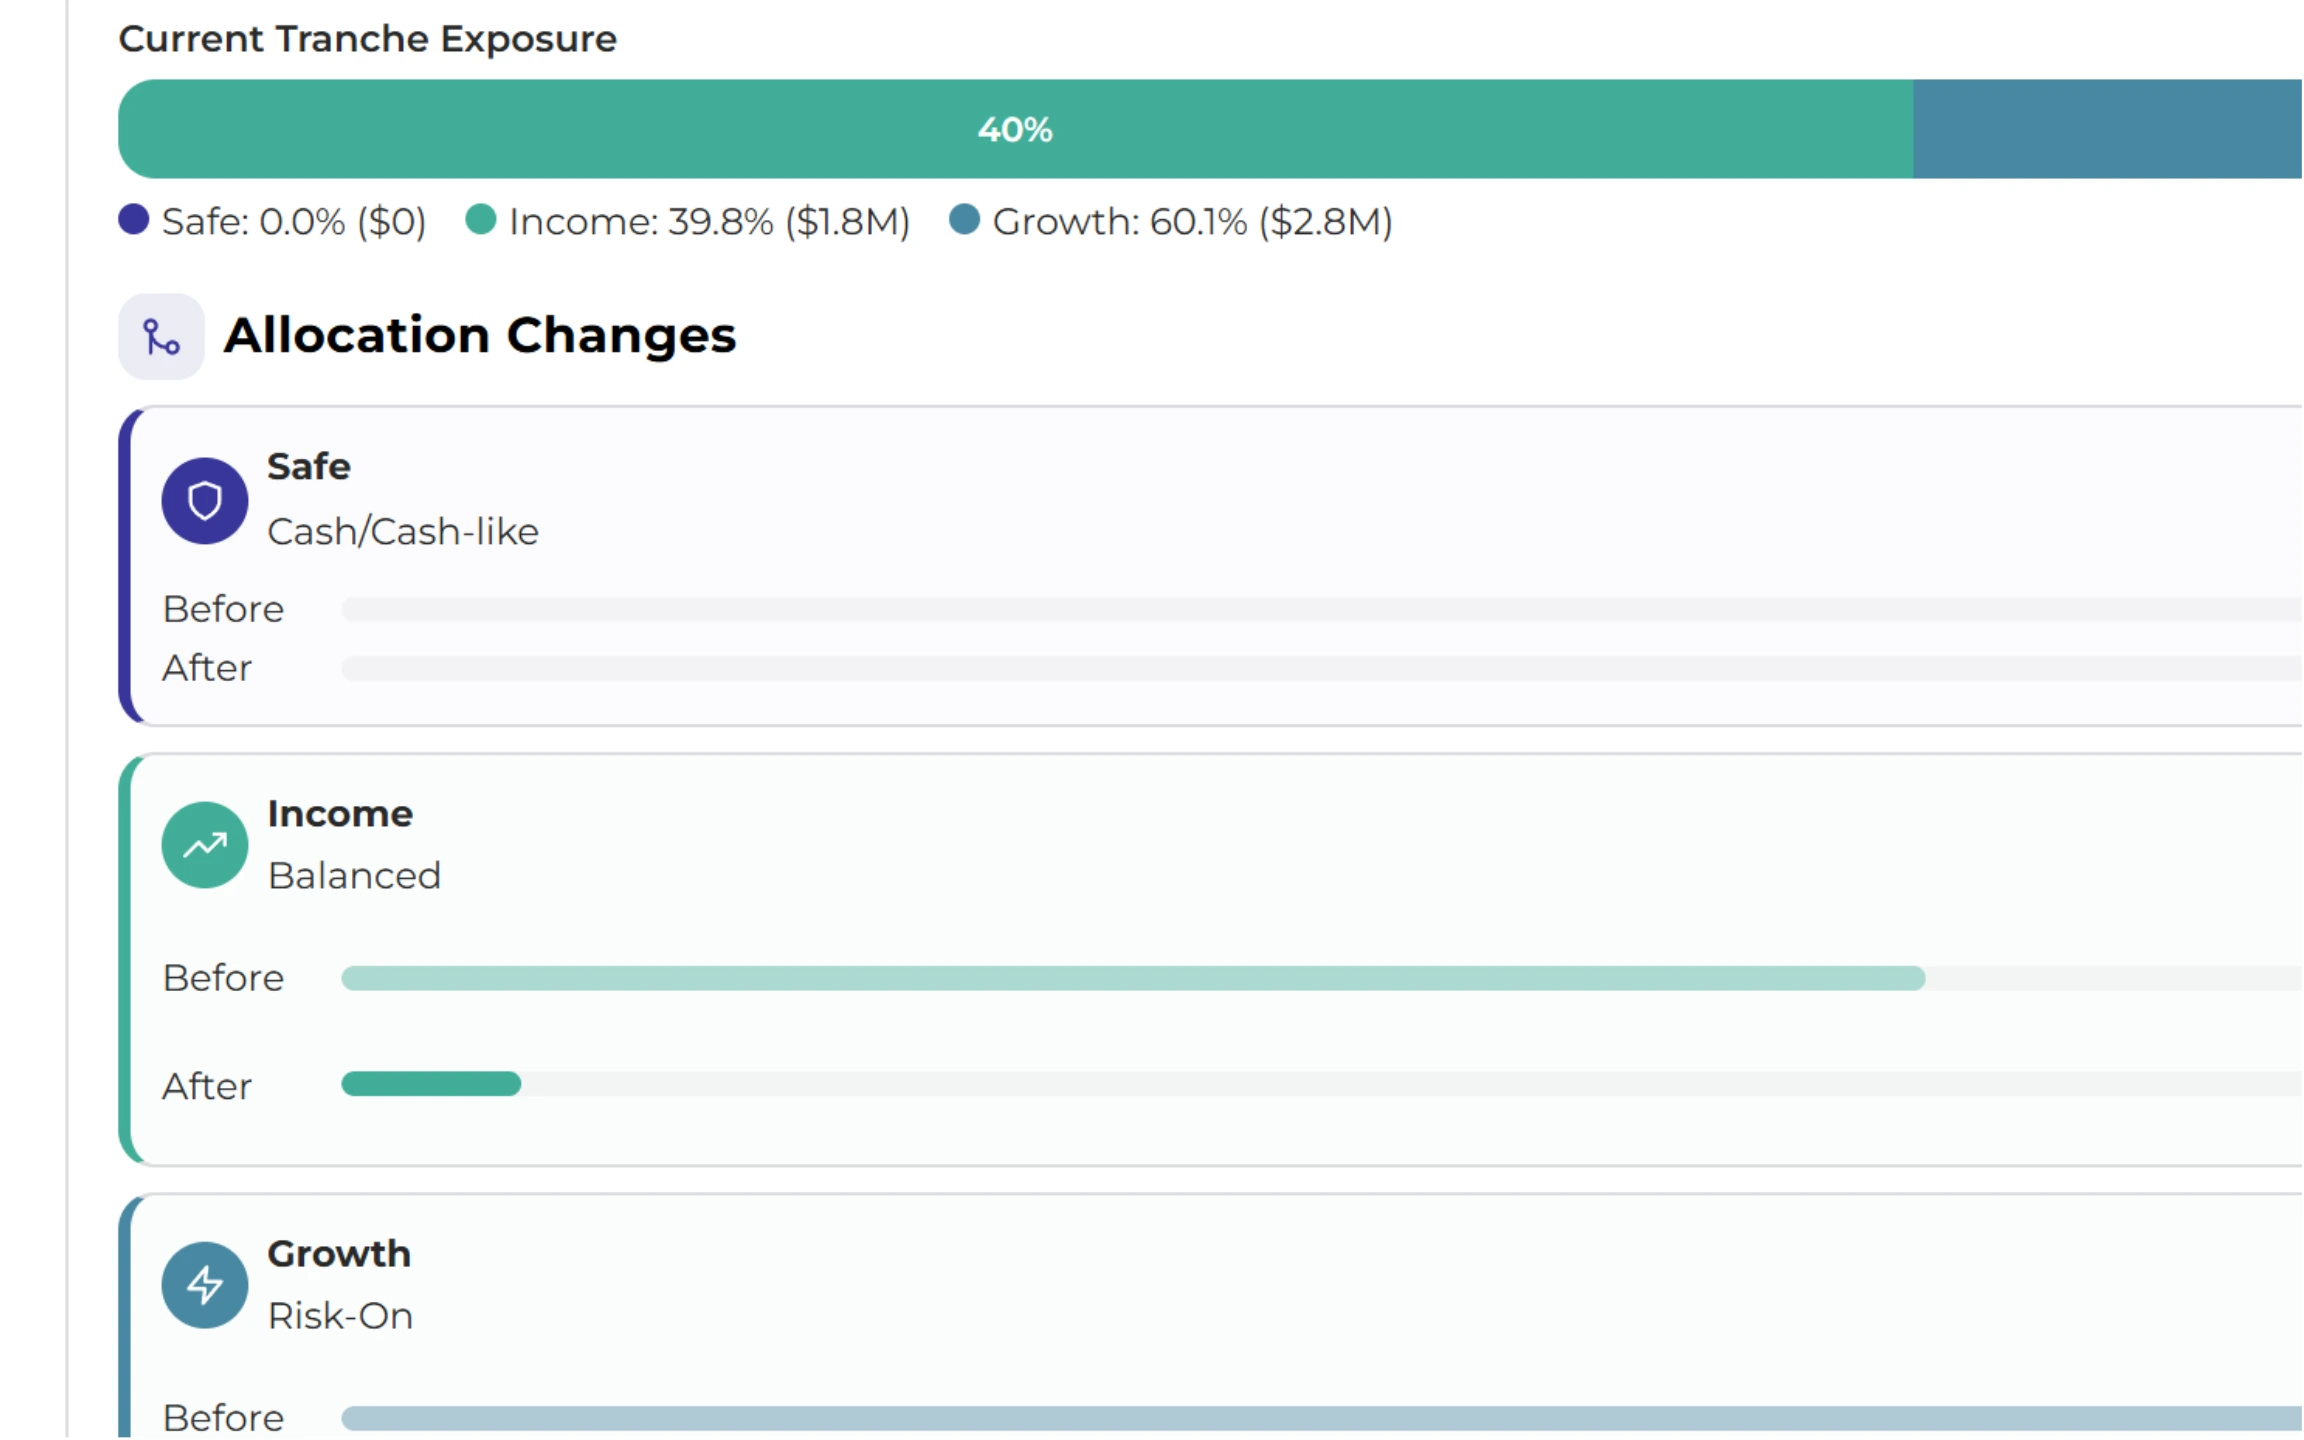
Personalized Portfolio Construction in Minutes
Build custom portfolios or let the system optimize. Set constraints, select from the model universe, and maximize growth with remaining assets after spending needs are covered.
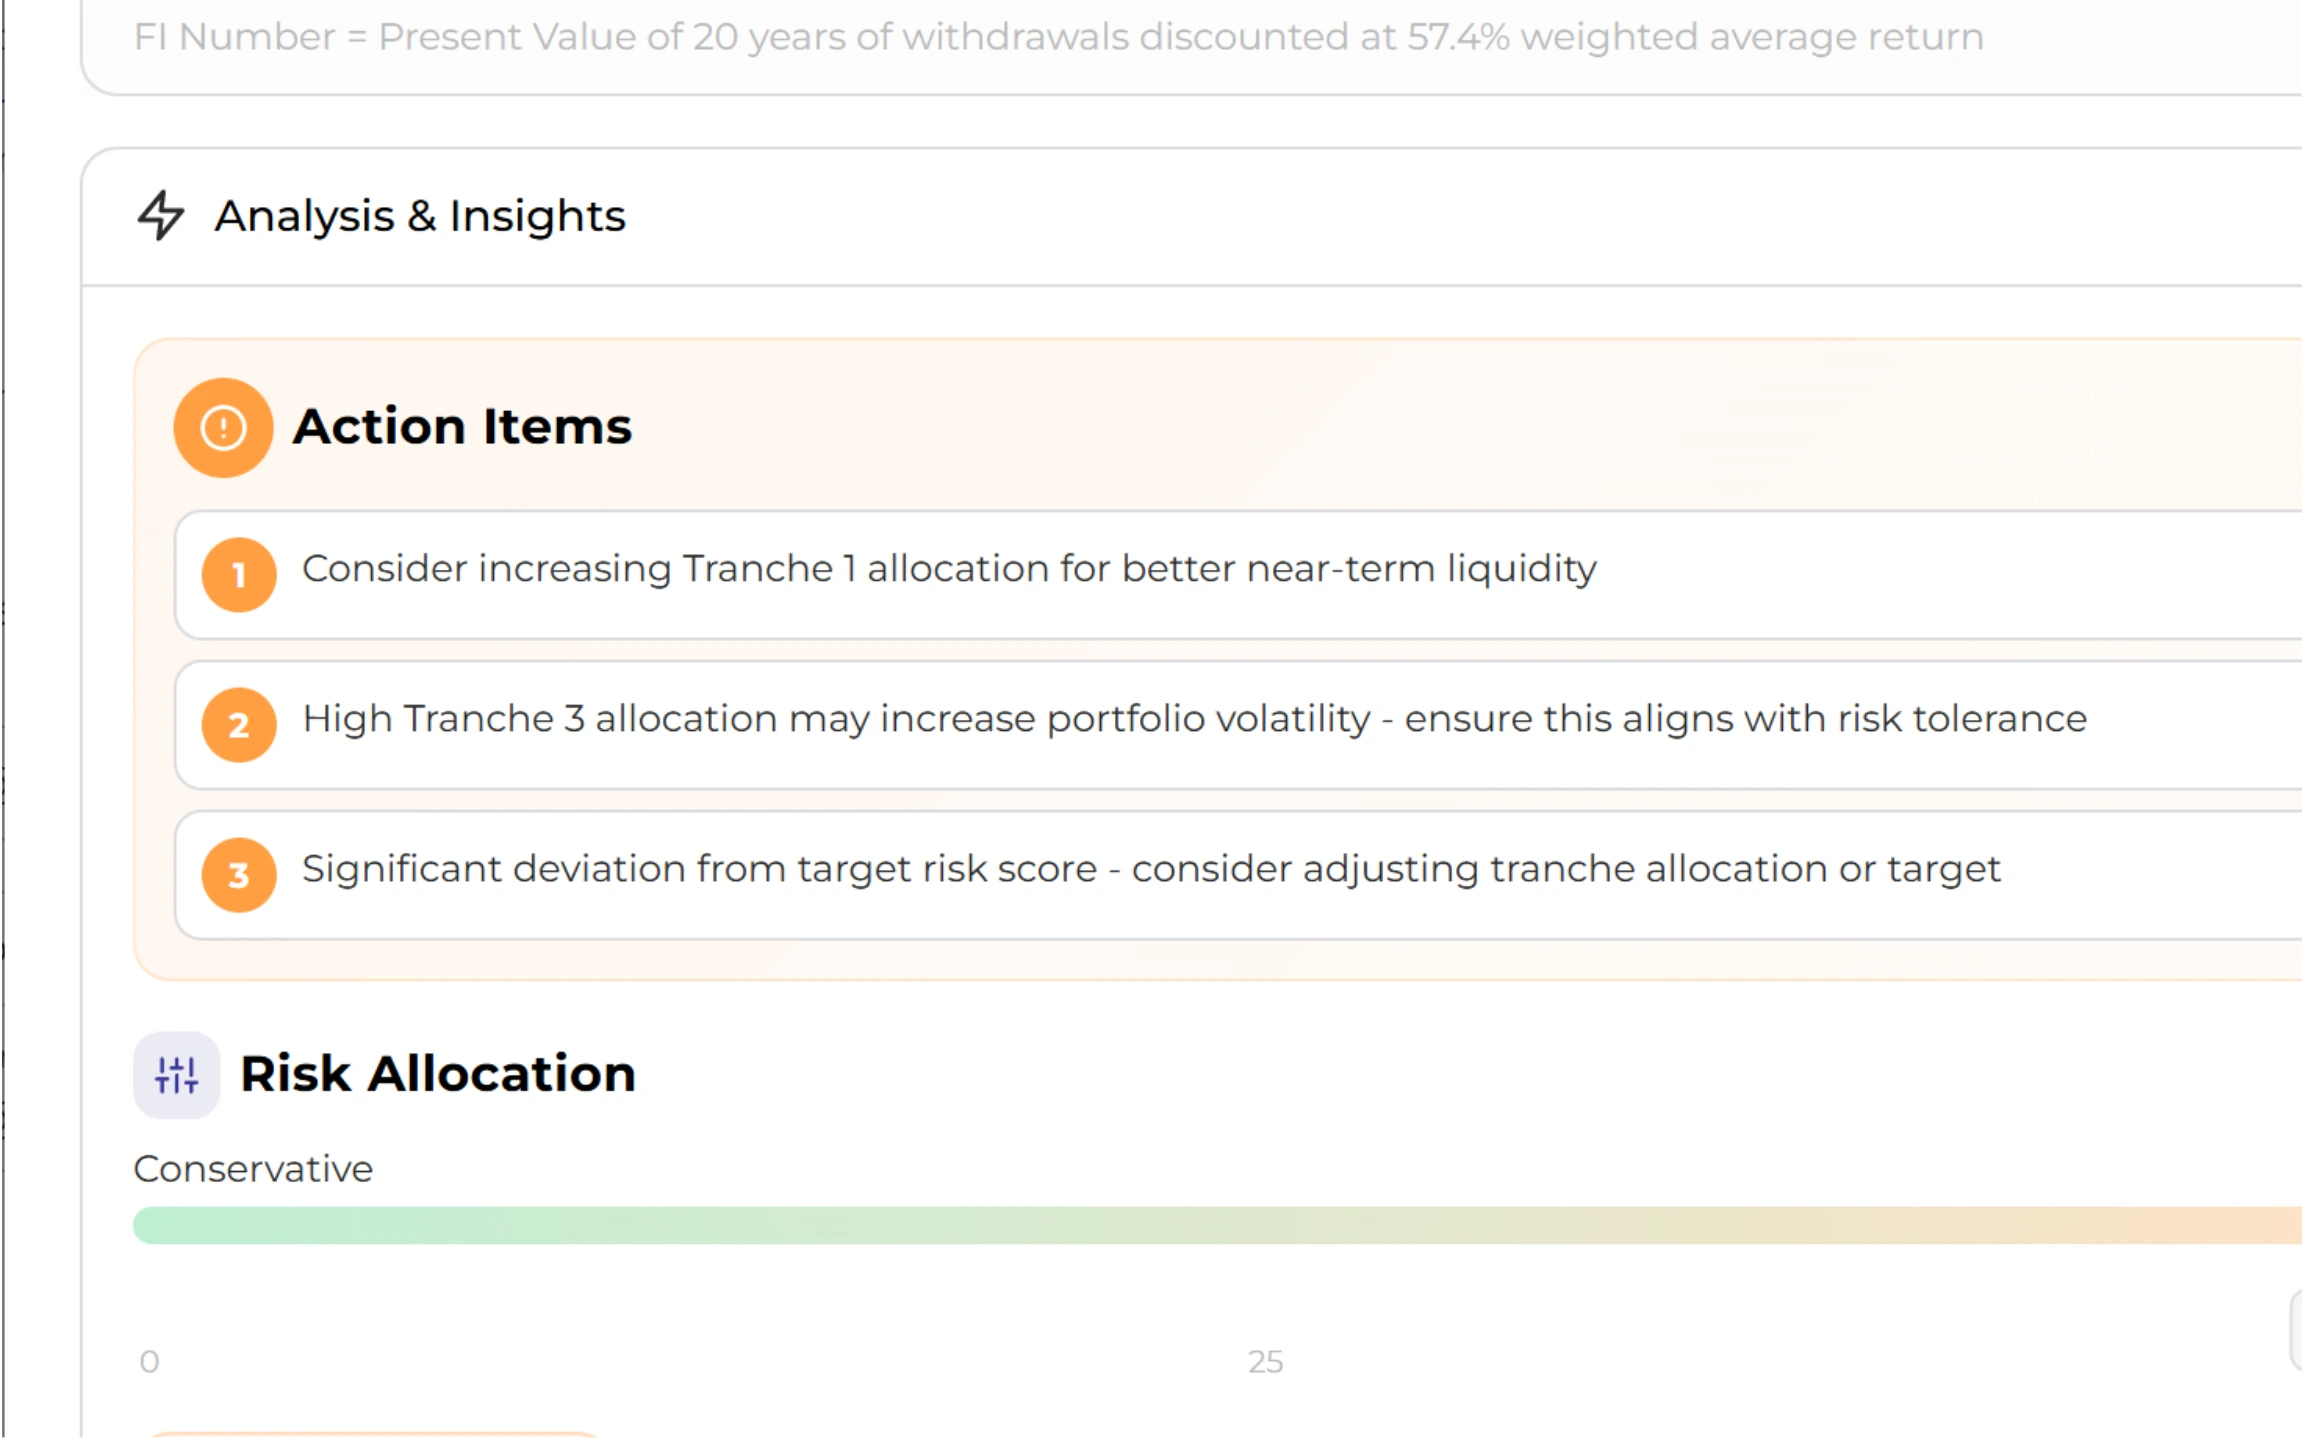
Track the Liquidity Runway
How many years of spending are covered? Which buckets need attention? Clear visualizations answer the real question, not pie charts.
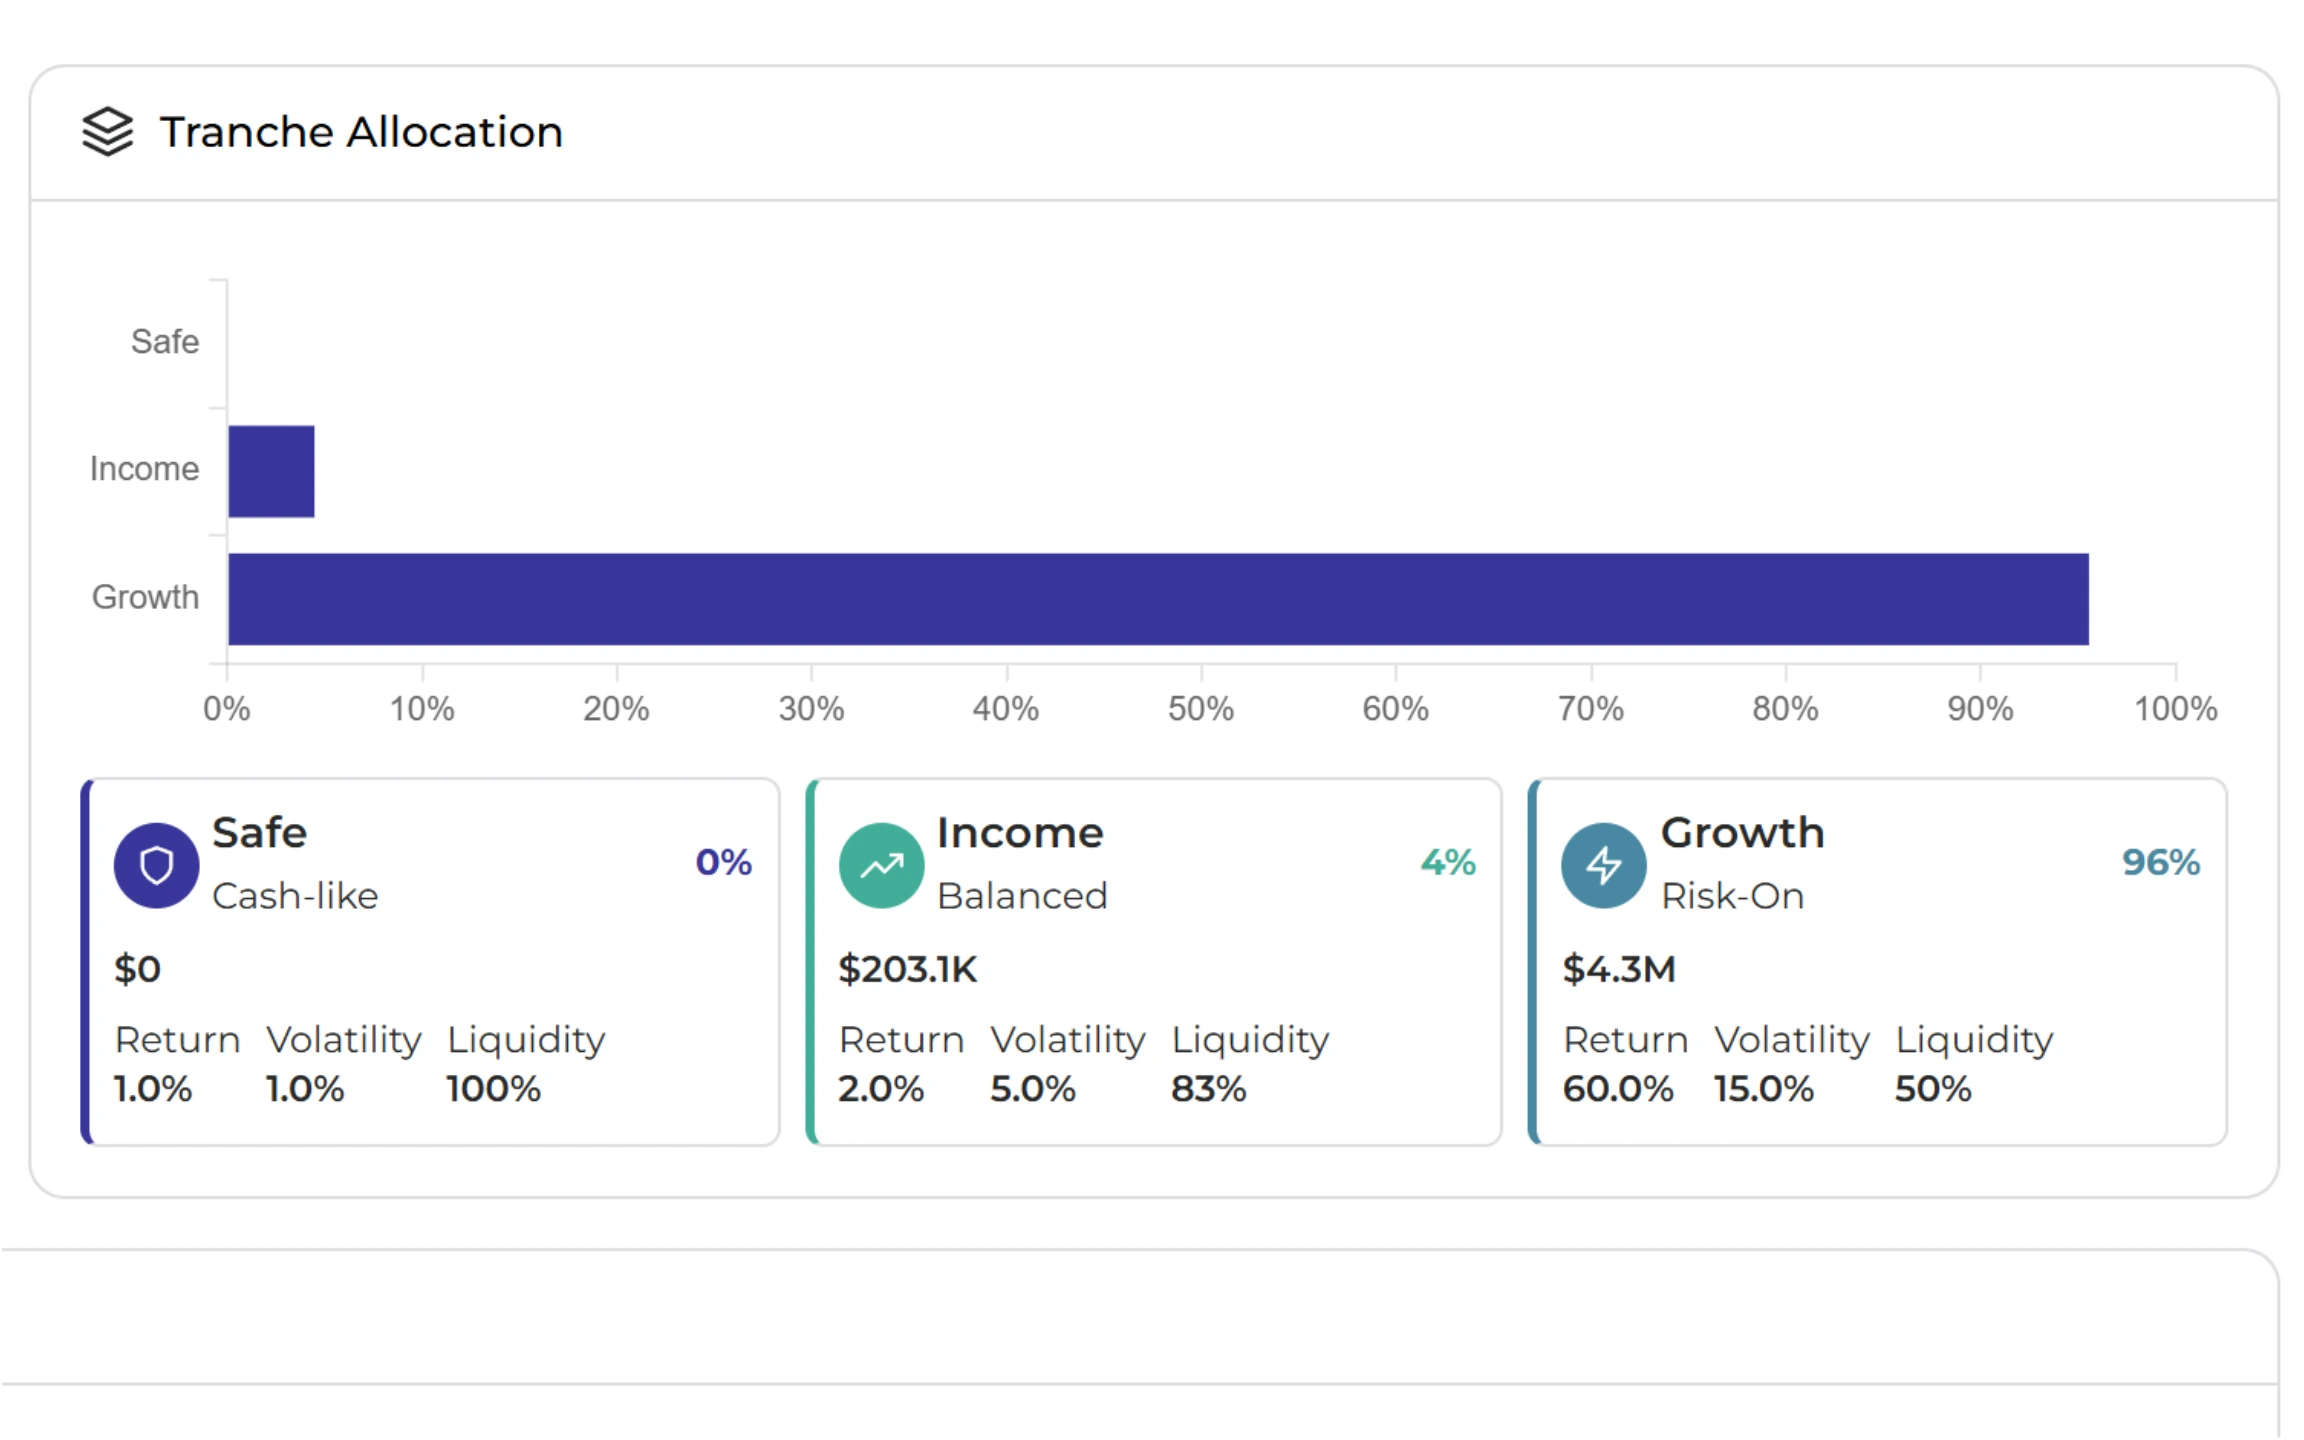
Trusted by financial advisors
See how practices are transforming their workflows
"We're deeply committed to integrating cutting-edge technology to transform the financial planning landscape. Investipal's innovative approach aligns perfectly with our vision, particularly in utilizing OCR technology to streamline processes and elevate the client and advisor experience."
ProsperPlan Wealth
"Investipal has completely transformed how we approach client onboarding and portfolio management. The AI-powered tools save us countless hours while delivering better outcomes for our clients."
Pacific Portfolio Advisors
"Investipal has been a game-changer for our firm. It really had become an efficiency multiplier for our assistants and back office. It's an indispensable tool for any advisory firm looking to thrive in today's competitive market."
William Joseph Capital Management
Frequently asked questions
Common questions answered
What is goal-based portfolio construction?
Goal-based portfolio construction matches assets to spending time horizons. Near-term expenses (0-3 years) are funded with stable, liquid assets like cash and short-term bonds. Medium-term needs (3-10 years) use intermediate strategies. Long-term assets (10+ years) stay invested for growth. This protects against sequence of returns risk while maximizing long-term growth potential.
How is this different from traditional asset allocation?
Traditional allocation (like 60/40) treats the portfolio as one pool without regard to when money is needed. Goal-based construction explicitly matches assets to spending timelines. This means near-term expenses aren't exposed to market volatility, reducing the risk of selling growth assets at the wrong time, a critical concern for retirees.
What happens when spending needs change?
Spending needs change: healthcare costs increase, travel plans shift, inheritance arrives. Simply update the spending inputs, and the system recalculates bucket allocations and optimization. Model scenarios before making changes to see how adjustments affect the overall liquidity runway.
How do advisors explain liquidity buckets to clients?
Clients intuitively understand "money for now, money for later, money for growth." Show them: "This bucket covers the next 3 years of expenses. It's in stable assets that won't drop 30% if the market crashes. This bucket is for years 3-10. And this is the long-term growth bucket." It answers their real question: "Will I run out of money?"
Does this work with systematic distributions?
Yes. Enter annual distribution amounts as spending needs, and the system ensures those amounts are covered by appropriate liquidity buckets. As distributions occur, the system tracks remaining runway and can alert advisors when buckets need replenishing from longer-term assets.
See Goal-Based Portfolio Construction in Action
Match assets to spending time horizons and build retirement portfolios clients understand.